
About Haydn:
Haydn is a dual-qualified solicitor and chartered accountant with over 2 years' experience. He is recognised as a leading individual in Legal 500 and recommended in Chambers for his commercial and practical tax advice.
If you're looking to pass on your wealth in a tax-efficient way, a family investment company could be a good solution for you. Talk to our expert solicitors to learn how a family investment company could help you.
Schedule a callA family investment company is a private limited company based in the UK, where all shareholders are family members and which invests rather than trades.
Family investment companies are becoming increasingly popular as a way to secure family wealth, being straightforward to set up and a flexible and very tax-efficient way to invest cash to generate income for the family, keep control of assets and pass them to the next generation — particularly if you're familiar with how a business operates. They are being used as an alternative to trusts for Inheritance Tax planning when an individual, typically, has cash assets of £1m plus.
A further attractive benefit is that family investment companies are taxed according to corporation tax rates, which are significantly lower than personal income tax rates.
If you'd like to consider a family investment company as part of your strategy for inheritance, succession and wealth planning to meet your family’s unique requirements, our expert solicitors can guide you through the legal process and help to ensure that your family investment company is fit for purpose.
Weightmans gives detailed and careful advice in addition to being responsive and quick to address the issues. The team has excellent knowledge and technical skill to deal with complex matters.
Chambers and Partners, 2026
Weightmans has a well-established and cohesive team, with broad and deep skills. The team members know their areas of expertise but also can tap into a global network of attorneys where necessary.
Chambers and Partners, 2026
The staff are very personable and easy to interact with, and generally good at interacting with our clients.
Chambers and Partners, 2026
My involvement with Weightman's has identified legal professionals who are responsive, highly skilled, approachable and pragmatic. I had great confidence in their guidance, organisation and judgement which was delivered clearly.
Legal 500 2026
Weightmans have a detail-oriented approach. They maintain meticulous records, ensure accuracy in legal documents and catch potential errors or inconsistencies before they arise.
Chambers and Partners, 2026
The team clearly work very well together and put clients' needs as a priority.
Chambers and Partners, 2026
Weightmans have an excellent communication style which builds trust and confidence among delegates.
Chambers and Partners, 2026
The advice from Weightmans is accurate, practical, delivered on time and in an exceptionally professional manner.
Chambers and Partners, 2026
I have been instructed by Weightmans as counsel. I have been impressed by the quality of the instructions which have identified the salient issues. The firm is responsive and easy to work with from the point of view of counsel.
Legal 500, 2026
This practice stands out for its exceptional expertise, innovative approach, and client-centered service. The team is known for being trustworthy, reliable, and highly knowledgeable, always prioritising clients’ best interests. Clients are kept well-informed every step of the way, empowering them with the insight and support needed to make confident, informed decisions.
Legal 500, 2026
Weightmans has exceptionally experienced and knowledgeable individuals.
Chambers 2025
I have been extremely impressed by their ability to receive a case at short notice and provide very effective legal representation throughout.
Chambers 2025
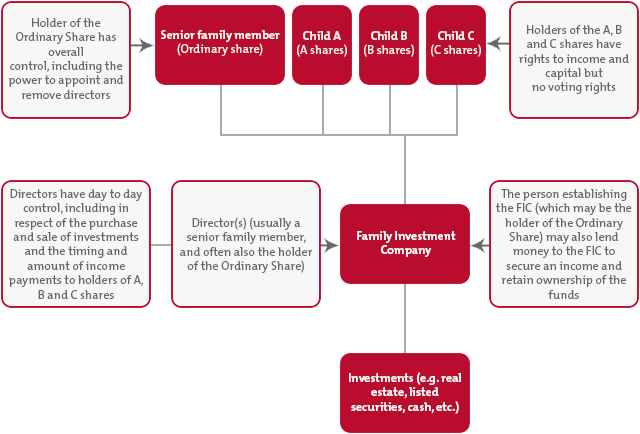
There is a great deal of flexibility as to how the family investment company can be structured but typically each family member who is to benefit from the family investment company will hold a different class of share. These shares give the family members the ability to receive such income (in the form of dividends) as the directors declare. The shares also provide an entitlement to capital (in defined amounts or proportions) in the event of a sale, return of capital or the winding up of the family investment company.
The founder of the family investment company will usually also hold shares. The founder’s shares would not normally carry any rights to receive significant value from the company (although if this is desired, to some extent, value can be retained by the founder), but do carry voting rights, giving the founder control over the appointment of directors. Where the founder is a director, he has control over how the company is run including the investment of assets and declaration of dividends.
The founder shares will pass on death in accordance with their Will which can provide a further layer of management and protection for family wealth.
Yes, a Family Investment Company (FIC) can buy and hold residential and/or commercial property but care should be taken to obtain profession planning advice before buying property through a FIC to help navigate complex tax and corporate rules.
There is no restriction on what FICs can invest in but they most commonly invest in stocks and shares. This is because dividend income from stocks and shares will not generally be subject to corporation tax within the FIC itself and, if this dividend income is not distributed out to the shareholders, can be reinvested thereby further increasing growth.
They can be used to hold rental properties (residential and/or commercial) but care is required, particularly in relation to transferring in any existing properties, to assess the tax implications of doing so. On occasion, FICs may also be used to make loans to other family companies (often trading companies).
Anyone who would like to use a company structure as a means of holding cash or investment assets for the benefit of their family. Often they will be used by business owners who are familiar with how companies operate.
This depends on the assets and will be dependent upon tax and structuring advice in relation to the FIC and how it fits into any overall estate planning. Funding a FIC by way of cash (either by way of a share subscription or a loan) is the most straightforward. Properties or investments can be transferred to a FIC, though this will usually give rise to capital gains tax implications and stamp duty land tax in the case of properties.
Yes, you can transfer existing assets into a Family Investment Company but this could trigger a charge to Capital Gains Tax and/or Stamp Duty Land Tax so it is advisable to obtain tax advice prior to or alongside any proposed transfer.
Often FICs will be set up with multiple classes of shares, each designated by a different letter of the alphabet. The different classes of shares can each have different voting, income (dividend) and capital rights to suit the desired objectives.
Where set up with multiple share classes, often individual family members will own a different class of share each. These shares can be owned personally by the different family members, or in some situations they can be held in trust for them. One advantage of using multiple classes of shares in this way is that the directors may pay different amounts of dividends to the various family members to suit their individual requirements and needs.
The people setting up the FIC will usually hold the voting shares (so that they retain control over what is invested in and (if and) when the other “family” shareholders can benefit via dividends etc), with the other family members (such as children) holding the shares with economic (income and capital) rights. Again however it is flexible and subject to the specific individual circumstances in order to suit the family’s needs and objectives.
By way of lifetime gifts, or on death in accordance with the shareholder’s Will (or the intestacy rules if there is no Will in place). Shares can either be given outright to individuals or can be held on trust for their benefit.
If the shares have any value, they will be subject to the usual inheritance tax rules. This means that if the person giving away the shares survives the gift by more than 7 years, then there is no inheritance tax to pay. However, if they do not survive a gift by 7 years, then the gift could be subject to inheritance tax on their death, calculated on the value of the shares at the date of the gift. There is a tapering relief once 3 years have passed from the date of the gift. FIC shares left by Will form part of a deceased’s estate, and if the inheritance tax threshold is exceeded, will be subject to 40% inheritance tax on their market value.
Lifetime gifts of FIC Shares will be subject to capital gains tax if the shares have increased in value since they were acquired. This means that any gain will be taxed at 18% or 24% (based on the current capital gains tax rates) depending on the individual’s income tax band. Gifts on death are not subject to capital gains tax, as a person’s death washes away all capital gain. This means that the person receiving the shares (or the trustees) receive the shares at the date of death value.
There is no minimum value for setting up a FIC, though consideration should be given to the cost of setting it up as well as the annual administration costs involved in company compliance and reporting. Given the ability of a couple to put up to £650,000 into a discretionary trust or trusts FICs do not generally tend to be used if the value is below £1m, but this is not a hard and fast rule.
FICs cannot be ringfenced against divorce and shares in a FIC that are held by a divorcing spouse are an asset that will be factored in the marital assets. Provision to help protect a FIC against relationship breakdown can be made in the FIC Articles, which can restrict how shares can be transferred and also give a right for other shareholders to buy back the shares if they were to end up out of the family’s hands.
Pre or post nuptial agreements should also be considered. The consequence of these provisions is that the value of the shareholding may be limited in the event of divorce, which can protect against their forming part of a divorce settlement.
FICs can be structured so that different classes of shares receive different amounts of capital on a winding up. For example, classes of shares can be set up that only receive their nominal value, whereas other classes of shares can be set up which will receive all the future increase in the value of the company. This enables the value of any initial shares that are gifted or future growth to be given away, so that after 7 years the value of any initial gift along with any future growth will not be subject to inheritance tax in the hands of the original shareholder/founder.
Unlike trading companies, FICs are subject to inheritance tax on the full value of the shares on death. However, minority ownership discounts can apply, which take into account the minority owner’s lack of control over the company. This discount can be very useful for general family estate planning and can result in substantial inheritance tax savings.
There is usually no immediate tax consequence of adding large cash sums to a FIC, whereas trusts are usually limited to a person’s available nil rate band (currently up to £325k), otherwise an immediate (20%) inheritance tax may be due.
If dividend income is to be retained within a (discretionary) trust, it would be subject to income tax, and further tax when paid out of the trust. However, if this dividend income was retained within a FIC, it would not be taxed at all.
Unlike trusts, the value of assets in a FIC are not subject to 10 yearly or exit inheritance tax charges.
FICs are subject to double taxation when non-dividend profits are extracted (i.e. rental income for example would be taxed at the corporation tax rate — currently up to 25% and then taxed again at the dividend rate (currently 8.75%, 33.75% or 39.35%) when extracted from an FIC, whereas it would only be subject to the marginal income tax rates if paid out of a trust.
Companies, in particular limited companies, usually have higher compliance requirements than trusts, though usually both must submit tax returns.
Unlimited companies are sometimes used for FICs, as they have lower Companies House reporting requirements, enabling details to be kept out of the public domain. In addition, with investment companies that only investing in stocks and shares, the limited liability protection that limited companies provide is of little or no benefit.
FICs, like other companies, have ongoing compliance requirements. Tax returns must be submitted each year, and accounts and confirmation statements filed each year with Companies House.
If the shareholders are all in agreement, they can change the company articles of association and restructure the shares. If they are not in agreement, it will depend on whether they have enough votes to do that under the existing articles. Any changes may also give rise to actual or deemed capital gains tax charges so specific tax advice will be required before making any changes. Any additional funds added to the FIC should also be made in the same proportions which may mean that, depending upon the particular circumstances, setting up a new, separate FIC may be the more tax-efficient option.
About Haydn:
Haydn is a dual-qualified solicitor and chartered accountant with over 2 years' experience. He is recognised as a leading individual in Legal 500 and recommended in Chambers for his commercial and practical tax advice.
About Jonathan:
Jonathan heads the International Private Wealth offering at Weightmans. Jonathan is a trust, tax and estates lawyer and deals with all aspects of personal estates, wills and tax planning for UK-based and international clients. Jonathan specialises in offering international private wealth advice.


